The serious case for retiring in France.

It rests on three things: care you'll actually use, a 1994 treaty that keeps your US retirement income taxed only at home, and day-to-day prices most US cities and towns stopped offering years ago.

The postcard, fact-checked.

What draws Americans here, with the numbers behind it.

1st
travel destination on earth

The world's favorite country

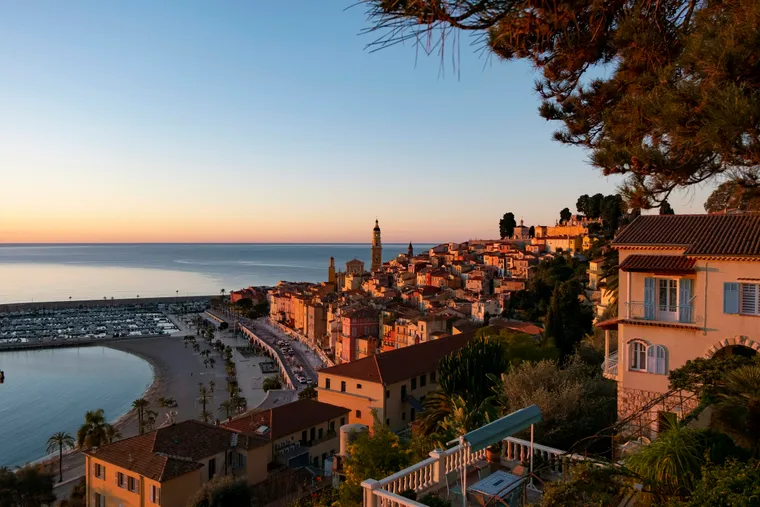
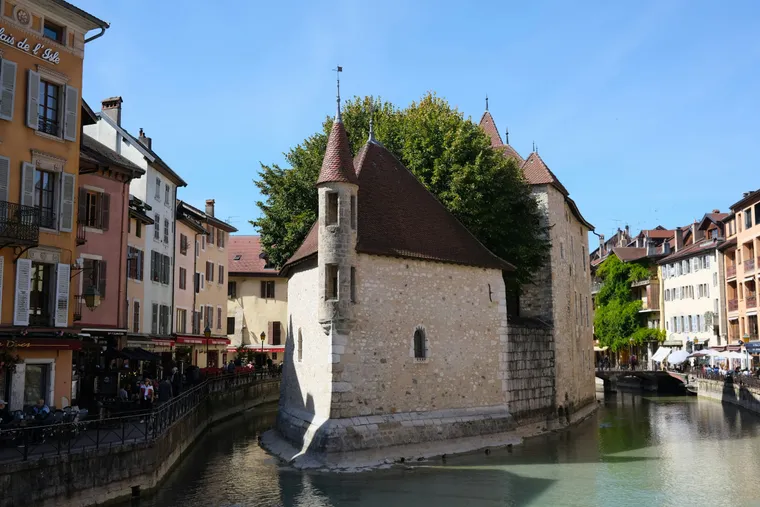
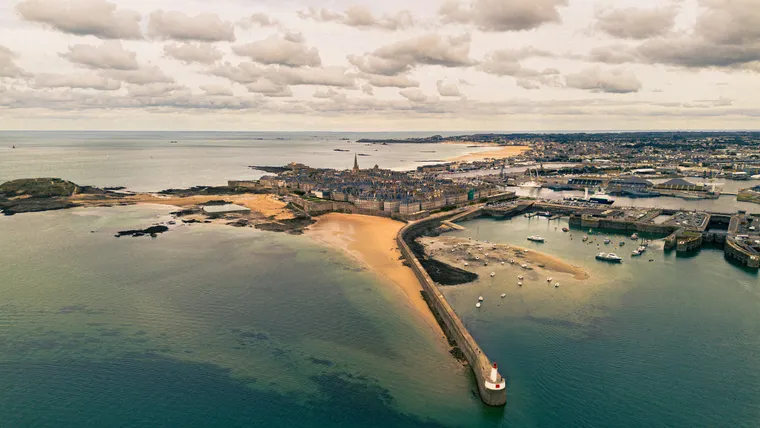
Thirteen regions, each with its own landscape and culture. Alpine peaks, Mediterranean coast, medieval villages. Castles and cathedrals, museums and markets — and, obviously, the food.

+4 yrs
life expectancy vs US (Source: UN)

Healthcare that still feels human

Get the care you need. No networks, no deductibles, no surprise bills. Universal coverage through Protection Universelle Maladie — France's public healthcare system. Residents are covered after 3 months. A separate health contribution can apply if you live mainly off investment income. plus a small Private complementary insurance that covers what PUMa doesn't; premiums rise with age. — at about half what the US spends per person (Source: OECD).

30%
lower cost of living vs US (Source: Forbes)

Prices for living, not visiting

France is expensive to visit, not necessarily to live. Away from central Paris, groceries, restaurants, doctors and everyday services cost less than in much of the United States.

Americans retiring in Europe usually pay more tax. In France, they often pay less.

In most European countries, tax residents pay local tax on their worldwide income. US tax credits prevent double taxation, but they don't stop you paying the higher rate between the two countries.

France is the exception — and only for Americans. Under the US–France tax treaty, US-source income (Social Security, 401(k), IRA, pensions, capital gains on US investments, and rent from US property) is taxed only by the United States. France doesn't layer its own tax on top. Then state tax drops off too: under US federal law (4 United States Code, Section 114) that blocks states from taxing the retirement income of non-residents. The provision that makes your former state drop off your tax return., your former state can't reach your retirement income once you've properly established non-residency. All of it is still declared in France each year.

Income tax your new country collects on a US retirement income
France
None
US-source retirement and investment income is taxed only by the US under the 1994 treaty. France adds no income tax and no CSG/CRDS on top.
Spain
19–47%
Worldwide income taxed at progressive rates — pensions and IRA withdrawals count as general income; investment income 19–28%.
Portugal
14.5–48%
The NHR scheme that drew retirees closed to new arrivals in 2025 — new residents pay standard progressive rates on pensions.
Italy
23–43% + local surtaxes
A 7% flat regime exists, but only in small southern towns, for ten years at most.
Tax outcomes depend on your income mix and personal circumstances; this is a high-level comparison only. One French charge sits outside the treaty: households living mainly off investment income can owe a health contribution (the “taxe PUMa”), which the calculator below accounts for. See our detailed guide for the underlying rules.

What people get wrong about France.

France has a reputation: expensive, hard to navigate without fluent French, a long way from home. For many American retirees, the reality is surprisingly different.

  1. “France is too expensive.”

    France is expensive to visit, not necessarily to live. Outside central Paris, many retirees find that groceries, restaurants, healthcare and everyday services cost less than in much of the United States. It's one of the biggest misconceptions we see.

    Worth remembering

    Outside Paris, Forbes estimates the cost of living is 30% lower than in the US.

  2. “Socialized healthcare means less choice.”

    French healthcare is publicly funded, not government-run. You still choose your own GP, specialists and hospitals. There are no insurance networks deciding which doctors you can see.

    Worth remembering

    France combines universal coverage with one of the highest life expectancies in the developed world, around four years longer than the United States.

  3. “You'll need to speak fluent French.”

    You don't. While learning French will make life richer, thousands of Americans move every year with limited French. English-speaking professionals are widely available in many parts of the country, and your language skills improve much faster once you're immersed.

    Worth remembering

    France welcomed 100 million international visitors in 2024. English is the most widely spoken foreign language in France, and nearly half of French adults say they can hold a conversation in it.

  4. “You'll be isolated from family and friends.”

    France is closer than many Americans imagine. Direct flights connect Paris, Nice, Marseille and Toulouse to major US cities, and once you're there, much of Europe becomes a weekend trip rather than a once-in-a-lifetime vacation.

    Worth remembering

    There are nonstop flights between France and numerous US gateways, and France's high-speed rail network connects major cities in just a few hours.

  5. “You have to live in Paris to enjoy France.”

    For many retirees, France becomes a base rather than a destination. Spend a month in Provence, a week in the Alps, Christmas in Alsace, or a weekend in Italy or Spain, all without changing countries permanently.

    Worth remembering

    France has 13 metropolitan regions, each with its own climate, landscape and culture, making it possible to reinvent your retirement without ever leaving the country.

Fifty-five towns, scored against the retirement you want.

Nine questions about the life you want, three minutes. We score fifty-five retirement-ready towns and cities on sixteen factors of official French data (sunshine hours, doctor access, real property prices, hospital drive times) and show our reasoning for every match, including the honest tradeoffs.

No email needed to see your matches. Every fact is sourced and dated.

See your own numbers.

Your household retirement income
Social Security
Taxed only by the US · treaty Art. 18
$35,000
401(k) / IRA withdrawals
Taxed only by the US · treaty Art. 18
$60,000
Roth IRA withdrawals
Tax-free in both countries
$10,000
Dividends / Rents / Capital Gains
US-source · no French income tax (a health contribution can apply)
$40,000
The state you're leaving
Assuming a typical ≈6% effective rate —
Effective state tax rate
Set it to match your last state return
6%
How you like to live
Pick the closest to your household's monthly spending today.
Your picture, in France
on $145,000/yr

US federal tax stays the same, since US citizens are taxed worldwide. What changes:

  • State tax drops to $0. Once non-residency is properly established, your former state can't reach your retirement income (4 U.S.C. §114). Most states already exempt Social Security, so we don't count it in this figure.
  • French income tax is $0 on US-source retirement income, capital gains, and US rental income — taxed only by the US under the 1994 treaty.
  • No CSG/CRDS (the 9.7% French social charges) on that income either.
  • One charge sits outside the treaty: once you're on French public healthcare with no pension income in the household, France can assess the cotisation subsidiaire maladie (the "taxe PUMa") — 6.5% on investment income above the first ~$26,000, or up to $910/yr on the income you entered. Retirees drawing Social Security or a pension have in practice been exempt. Your advisor confirms which side you're on.
Why the same life costs less in France:
Healthcare
PUMa + mutuelle replace Medicare, Medigap, Part D, and dental, at a fraction of the premiums.
Housing
Comparable homes rent for 30–50% less than in US metros, outside Paris.
Getting around
Trains and walkable towns replace car ownership. Many couples drop to one car, or none.
Food & dining
Groceries run ~35% cheaper, and restaurant prices already include tax and tip.
Plus utilities, insurance, and entertainment, partially offset by higher cross-border tax prep. Aelos' spending comparison of a typical household measured ~45% lower costs; we apply the more conservative 30% that Forbes reports for life outside Paris to the lifestyle you picked. Your advisor will model your actual mix.
Your total annual savings
$34,800
Over
years
$870K
Email yourself these numbers

Rough estimate for illustration. Assumes properly established French residency and non-resident state status. Cost-of-living savings apply Forbes's 30% figure for life outside Paris to the lifestyle you picked. Not netted out above: a possible French health contribution (the "taxe PUMa") of up to $910/yr on investment income. It mainly applies to households without pension income, recurs yearly against the multi-year figure, and isn't offset by the treaty. Your advisor will model your actual situation.
Already in France? This is the same math Membership keeps current for you, year after year.

Book a free call with an Aelos advisor.

Thirty minutes, no pitch. About a third of these calls end in “not now,” “do it yourself,” or “France isn't right for you.” If it is right, you'll leave knowing exactly what to do next.

Ali Benslimane
Ali Benslimane
Aelos co-founder. Every consultation is with Ali, not a sales team.
30 minutes · free · no obligation
What we'll cover
  • 01Your personal tax picture, both countries
  • 02Visa and residency strategy
  • 03Healthcare planning and enrollment
  • 04Cross-border estate planning considerations
  • 05A clear next step — Go/No-Go if you're planning, a gap review if you're already in France

Two years from the move, or three years past it? The rules keep moving.

Treaty changes, visa updates, healthcare shifts, and stories from members already living in France. A free newsletter, straight to your inbox, whether you're still planning or long since landed.

Free. No spam. Unsubscribe anytime.

Retiring in France, explained.

Read all articles →
Housing

Can Americans Buy a House in France? A 2026 Guide

Yes, Americans can buy property in France, including as non-residents. What the purchase actually involves, the costs, mortgages, taxes, and why owning a home is not the same as the right to live there.

Ali Benslimane · October 4, 2026